Gavekal Research

Most recent

Geoeconomic Monitor: Russian Hopes, Chinese Fears
Gavekal Research

Lock

Geoeconomic Monitor: Russian Hopes, Chinese Fears

Tom Holland, Tom Miller, Udith Sikand
16 Oct 2026
Donald Trump has high hopes that his putative deal with Vladimir Putin to resume Russia’s exports of diesel will bring down global—and US—prices. But, as Tom Holland explains, it will not be enough to restore “normality” to global diesel prices into 2027. In addition, Tom Miller examines the US government’s attempt to forge a trade bloc to counter Chinese industrial overcapacity, and Udith Sikand looks at the impact of Washington’s latest restrictions on the H-1B visa program.
Going Back To An Old Tool

Gavekal Research

Lock

Going Back To An Old Tool

Charles Gave
16 Oct 2026
Those who were managing money in the 1970s and are still active today may remember a tool developed by economist Arthur Okun during that decade: the so-called “Misery index”. The idea was simply to add the unemployment rate to the inflation rate to produce the Misery index. At the time of writing, the US Misery index, based on the consumer price index, stands at 7.88, well below the critical level of 10. So, is everything fine? Maybe not.

Gavekal Dragonomics

Lock

The Fruit Of Tariffs Is Fraud

Thomas Gatley
16 Oct 2026
While on the surface it appears that eight years of tariffs has led to a material decoupling of US-China trade, Thomas argues that this is a fiction. China’s exporters and US importers have found two important ways to minimize the amount of tariffs they pay, meaning the true value of Chinese-made goods flowing into the US is likely in excess of US$600bn annually—more than twice as much as US Customs reports.

Gavekal Research

Lock

Video: The US Supply Response

Tan Kai Xian
15 Oct 2026
US manufacturing capacity and production are both improving, but the country remains far from being able to meet more of its domestic demand. In this video interview, Kai Xian explains why labor shortages, compounded by tight immigration policies, are a bigger obstacle to expanding US manufacturing than a lack of physical capacity. With Washington pressing other countries to curb excess production, the risk is that trade restrictions drive US inflation even higher, rather than deliver the intended revival in domestic manufacturing.

Gavekal Dragonomics

How Late Payments Became A Permanent Problem
Lock
Andrew Batson, Xiaoxi Zhang
A Speed Limit For EV Development
Lock
Ernan Cui
The Other Energy Shock
Lock
Wei He
A Two-Track Property Stabilization
Lock
Xiaoxi Zhang
An Unbalanced Earnings Cycle
Lock
Thomas Gatley

Gavekal Research

Another Leg Up In US Inflation?
Lock
Tan Kai Xian
Heads, Or Tails?
Lock
Louis-Vincent Gave
The Cost Of Protection
Lock
August Gudmundsson, Cedric Gemehl
Emerging Markets’ Second Balance Sheet
Lock
Rohan Daswani
The Curse Of Good Intentions
Lock
Udith Sikand

Gavekal Technologies

China’s Growing Grip On Printed Circuit Boards
Lock
Laila Khawaja
Can China Export Its Nuclear Boom?
Lock
AJ Cortese
Capitalizing On China’s Data Advantage In AI
Lock
Laila Khawaja
Great Tech In Search Of Profits
Lock
AJ Cortese, Laila Khawaja
GavekalTech On The Ground: 2026 China Tech Trip Takeaways
Lock
Laila Khawaja

Gavekal-IS

The Big Neutral
Lock
Didier Darcet
Why Aren’t Stocks Plunging?
Lock
Didier Darcet
Amathia
Lock
Didier Darcet
When Asia Revalues…
Lock
Didier Darcet
Where Does The Money Go?
Lock
Didier Darcet

Gavekal Research

Lock

Desperately Seeking An Anchor

Charles Gave, Louis-Vincent Gave
14 Sep 2026
Charles and Louis argue that a new monetary anchor is emerging in Asia, centered on the renminbi, just as Western currencies and bond markets are becoming less reliable stores of value. With most of the world’s excess savings generated in Asia, more capital will stay in the region rather than flow into Western assets, eroding structural support for the US dollar, euro and Western bond markets.

Checking The Boxes

Our short take on the latest news

Fact
Surprise
Takeaway

US PPI rose 6.3% YoY in Sep, versus 5.6% in Aug

Above expected 5.4%; PPI ex-food & energy rose 5% YoY in Sep, versus 4.8% in Aug

Driven mainly, but not only, by rising energy prices; expect further Fed tightening

US retail sales in nominal terms rose 0.8% MoM in Sep, versus 1.3% in Aug

Above expected 0.3%; retail sales ex-auto & gas rose 0.2% MoM in Sep, vs 1.1% in Aug

Energy prices buoyed headline reading; underlying trend still positive amid wealth effects

Eurozone industrial production fell -0.5% MoM in Aug, versus -0.3% in Jul

Below expected 0%; YoY, industrial production fell -1.1% in Aug, versus -0.3% in Jul

Idiosyncratic country weakness drives drop; other indicators point to ongoing recovery

India trade deficit widened to -US$30.2bn in Sep, from-US$26.9bn in Aug

Above expected -US$30.3bn; exports (23% YoY) rose faster than imports (8% YoY)

Weak INR helping to buoy exports and partly offset energy shock

Test Your Knowledge
Which political leader is looking to trademark their voice?
  1. Japanese prime minister Sanae Takaichi
  2. Nepali prime minister Balendra Shah
  3. President of the European Commission Ursula von der Leyen
  4. Italian prime minister Giorgia Meloni
Post Your Answer

Chart of the Week

Week 42, 2026
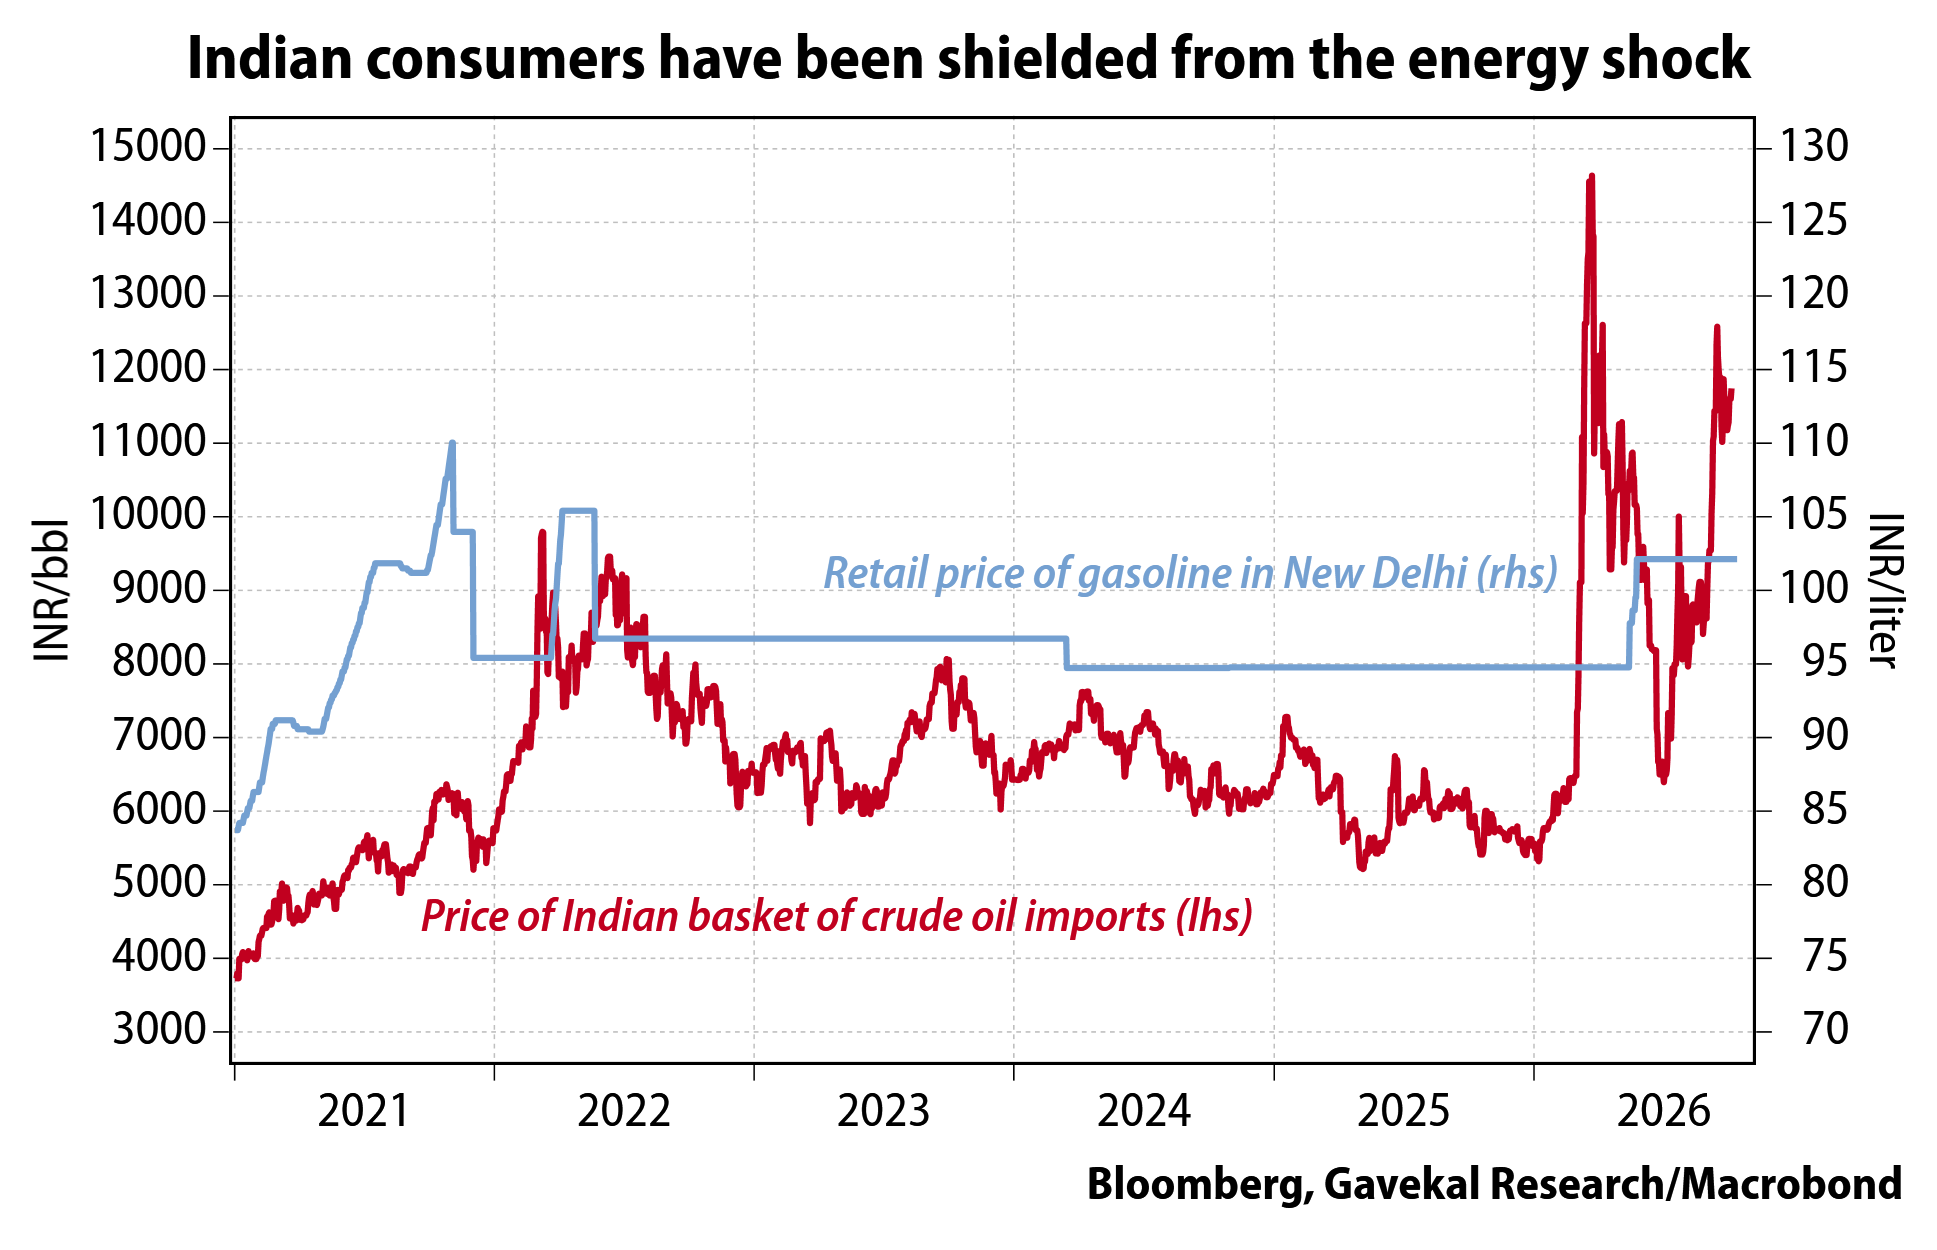
So far, India has cushioned the impact of the energy shock by forcing state-owned refiners to bear losses from selling fuel at below-market prices. This strategy will prove unsustainable if oil prices do not fall within the next few months, forcing a choice between higher retail fuel prices and greater fiscal support. Already the inflation outlook is worsening amid fears that a weak monsoon will push up food prices. That could compel the Reserve Bank of India—which earlier this month hiked rates for the first time in three years—to respond more aggressively. That, in turn, may snuff out the nascent recovery in private-sector investment.
Open Chart

Gavekal Research

Essential Reading: A Book For Every Week Of The Year

Gavekal is often asked for a recommended reading list. So, here it is: a book a week that everyone interested in the world of macro investing—whether hoary veteran or eager apprentice—can benefit from reading.

Gavekal Research

Lock

Webinar: Bond Market Blues

Anatole Kaletsky, Will Denyer, Cedric Gemehl
9 Oct 2026
Holders of developed world bonds experienced a world of pain in the third quarter of 2026, with long-dated US treasuries making a loss of -7.6% and equivalent French bonds down almost -15% in US dollar terms. In this webinar, founding partner Anatole Kaletsky, US chief economist Will Denyer and European economist Cedric Gemehl examine the forces driving the brutal sell-off in major debt markets and ask whether the time is approaching for investors to buy bonds once again.

The Iran War And Fallout

The Non-Threatening Energy Crisis
This weekend’s media made for sobering reading. Between bombs flying in the Middle East, more refineries blowing up in Russia and US senators calling for petroleum export bans, it felt like enough negative news flow to send hearts racing. But most major global equity markets remain close to all-time highs. Louis examines the possible reasons for this counterintuitive configuration.
Lock
No Good Outcomes For Energy Inflation
It is Wednesday. Warring parties in the Middle East are again exchanging fire, and energy prices are spiking. For investors, it may be tempting to shrug off the latest flare-up, but disregarding the latest escalation in the Persian Gulf would be rash. Developments in the region will matter greatly for the trajectory of inflation over the coming months, and therefore for financial markets.
Lock
The Record High Diesel Prices
Because of soaring crack spreads, diesel prices everywhere around the world are making new all-time highs, at least in nominal terms. In real terms, the diesel price is still lower than the 2022 spike that followed the start of the Ukraine war. But Louis points out that with a real term diesel price above US$5/gallon, few good things happen.
Lock
The Limits Of Economic Fury
The US administration is now switching its focus to a campaign of “economic fury” in an effort to achieve its strategic aims against Iran. It is not obvious that this latest phase of the conflict is any more likely to result in a quick and easy US victory than the kinetic war. However, the economic implications of a prolonged stand-off may be less ominous than they at first appear.
Lock

US economy & markets

Another Leg Up In US Inflation?
US inflation accelerated in September, with the headline consumer price index rising 3.7% year-on-year, up from 3.4% in August. Looking ahead, geopolitics and energy prices will, of course, remain key swing factors for inflation. But beyond energy, the question for investors and policymakers is whether price pressures will spread through the economy, pushing up long-term inflation expectations, as some Federal Reserve officials fear. Two scenarios are worth considering.
Lock
Hedging US Growth Stocks
US growth stocks have proved remarkably resilient, with the MSCI US growth index generally outperforming its value counterpart since 2007. But when everything is going well, prudent investors look for potential pitfalls. So, what could derail the strength of US growth stocks, and how to hedge against these risks?
Lock
Are Yields Rising Too Fast For Banks?
US bank stocks have lagged the broader equity market since the start of September, with the S&P 500 bank index down -7.5% against a 1% gain for the S&P 500. Curiously, this has happened during an inflationary boom, which should favor banks. While higher yields typically benefit lenders by allowing them to charge more on loans and earn higher returns on their securities holdings, a rapid rise in yields can break things and hurt the sector. KX argues there are reasons to think these concerns will prove short-lived.
Lock
Are US Long Bonds A Buy? (Part IV)
US bonds face an unappealing near-term backdrop of persistent inflation, Fed tightening and heavy public and private-sector issuance. Yet unlike in 2022, valuations now favor bonds over equities, while rising real yields are approaching levels that could start to constrain capital spending and growth. For Will, this argues against going overweight bonds, but makes a neutral position increasingly attractive as a hedge against a sudden change in the investment environment.
Lock

China chartbook

Gavekal Dragonomics

Lock

Macro Update: Pushed And Pulled

Wei He, Dragonomics Team
3 Aug 2026
China’s economy is being pushed and pulled by two external shocks: the supply shock from the Iran war and the demand shock from the AI capex boom. Both are creating lots of volatility in trade flows, prices and profits, although the underlying trend of the domestic economy has not yet changed much. Neither are China’s policymakers showing much sign of significantly changing course. In our latest quarterly chartbook, Wei and the Dragonomics team diagnose the current situation and the policy outlook.

India chartbook

Gavekal Research

Lock

India Corporate Update: Waiting For Capex

Rohan Daswani, Udith Sikand
28 Aug 2026
India remains one of the world’s strongest growth stories, supported by resilient domestic demand, improving corporate balance sheets and strong credit growth. Yet as the boost from public infrastructure investment fades, the big question is whether these strengths can finally translate into a sustained revival in private investment. Rohan and Udith assess the prospects for that transition and the implication for Indian equities, where performance is increasingly diverging across sectors.

Latest video

Gavekal Research

Lock

Video: The US Supply Response

Tan Kai Xian
15 Oct 2026
US manufacturing capacity and production are both improving, but the country remains far from being able to meet more of its domestic demand. In this video interview, Kai Xian explains why labor shortages, compounded by tight immigration policies, are a bigger obstacle to expanding US manufacturing than a lack of physical capacity. With Washington pressing other countries to curb excess production, the risk is that trade restrictions drive US inflation even higher, rather than deliver the intended revival in domestic manufacturing.

Strategy Chartbook

Gavekal Research

Lock

Quarterly Strategy Review: 3Q26

Louis-Vincent Gave
5 Oct 2026
After the third quarter saw a brutal sell-off in major government bond markets, with yields breaking out to a generational high, Louis takes stock. In this Quarterly Strategy Review, he examines the forces driving the sell-off and asks the key questions facing investors everywhere.

Emerging markets

EMs Are The New DMs
Emerging-market bonds have dramatically outperformed their developed-market peers since 2020, helped by greater policy credibility, deeper domestic financial markets and reduced reliance on foreign investors. With DM bond yields now hitting multi-year highs, policymakers may increasingly look to the EM playbook, including softer forms of financial repression, to stabilize their markets, says Udith. From the US to Japan, signs of this shift are already emerging, suggesting that EMs may have a thing or two to teach DMs.
Lock
Video: Are EMs Back?
It’s been a good quarter for the broad emerging markets complex. The MSCI EM index has returned almost 7% in US dollar terms, while US equities are down by some -3.5%. So should investors jump on the EM train? Udith points out that there is a wide divergence in the performance of individual emerging markets, and the threat of tariffs hangs heavy over EM corporate earnings. Investors need to be selective.
Lock
Video: Southeast Asia Under Trump 2.0
Global investors are rightly focused on the potential losers from the United States pursuing an aggressively protectionist trade policy agenda, but there may be winners as well. Tom went in search of such economies last week. Today he explains how such “swing states” are likely to perform in an intensified period of great power rivalry between the US and China.
Lock
China Turbocharges EM Investment
As the rich world pulls up the protectionist drawbridge, investors risk missing a bigger story in emerging markets. Here, Chinese outbound investment is rebounding after the fallow Covid years, and is driving a new wave of industrialization that promises to lower the cost of the green-energy transition.
Lock

Europe's economy

The Cost Of Protection
China appears to have accepted export restraints on hybrid cars in exchange for the European Union dialing down its confrontational trade rhetoric. However, a de-escalation in rhetoric should not be mistaken for a retreat from the protectionist impulse taking hold within the EU. Germany’s hardening stance toward China has brought Berlin closer to Paris and revived the Franco-German axis as a driver of EU policymaking.
Lock
Three Tests For French Spreads
After touching 150bp last Friday, October 2, the 10-year OAT-bund spread retraced to 127bp on Tuesday, before widening again to 139bp Thursday. Rather than beginning a meaningful tightening, the spread appears to be undergoing a repricing which is likely to see it settle somewhere between 125bp and 300bp. However, this is a remarkably broad range. So, what forces could push spreads towards either the floor or ceiling of this band over the coming months?
Lock
Reasons To Start Buying Bonds
After four and a half years of steadfast bearishness on bonds, Anatole argues that after the latest sell-off, the relentless rise in US yields may be coming to an end—at least for the next year or two. This is not because fundamentals have improved. Rather it is because the bond market no longer trades on fundamentals, but on short term expectations of Federal Reserve policy, and the Fed has a mandate to preserve US government solvency. In this report, he explains why it now makes sense to start buying bonds again.
Lock
How Wide Can French Spreads Get?
Over the last three weeks of September, the sovereign yield spread between 10-year French OATs and 10-year German bunds widened 40bp, hitting 127bp on Wednesday. That is a gap last seen in June 2012, just weeks before Mario Draghi’s “whatever it takes” speech. Inevitably, therefore, France’s current bond market stresses have evoked memories of the euro crisis, and left investors wondering: just how wide could French spreads get this time around?
Lock

Equities

Where The US Is (Still) Exceptional
Lock
Profit Maxing And Social Anti-Fragility
Lock
The (Better) Case For European Banks
Lock
Should Equity Investors Be Reassured By Record Corporate Profits?
Lock
Important Recent Developments
Lock
A Buy Recommendation
Lock

Fixed income

How Wide Can French Spreads Get?
Lock
The Biggest Hot Potato In History
Lock
Video: The Challenge For Fixed Income Investors
Are US Long Bonds A Buy? (Part III)
Lock
Video: The Bond Market’s Big Question
Lock
Video: Breakdown Or Buying Opportunity For US Bonds?
Lock

From the archives: oldies but goodies

Deficit Deniers Of The World Unite
Gavekal Research
Lock

Deficit Deniers Of The World Unite

Anatole Kaletsky
In our politically correct age the pressure to bow down before certain popularly accepted and apparently proven “truths” can be overwhelming. In the aftermath of the US elections, two such nostrums are unnecessarily vexing investors—the urgency of deficit reduction and fear of higher taxes. I believe that both of these obsessions will soon be forgotten.
More
Are We Entering into Revolutionary Times?
Gavekal Research
Lock

Are We Entering into Revolutionary Times?

Louis-Vincent Gave
The role of a society’s elite is to rise to the challenges of the times, and find solutions fitting to those times, even if this involves a radical break with the past. But the modus operandi for most leaders is to try and maintain the status quo. But if the problems are large enough, this does not work, and the same challenges reappear until either a solution is found, the elite is replaced by a new elite, or the country, system or civilization disappears.
More
The High Cost Of Free Money
Gavekal Research
Lock

The High Cost Of Free Money

Charles Gave
Perhaps the most famous economic law is the one that there is no such thing as a free lunch. By keeping US short rates at abnormally low levels beyond the financial crisis and as growth bounces back beyond the dreams of the wildest optimists, the Fed increasingly seems to be trying to ‘feed the US economy for nothing’. This is worrying, for extended periods of cheap money typically come back with a hefty price tag.
More